Personal Finance Tips for 2026: A Practical Plan to Build Real Wealth
Good money habits are not about deprivation, they are about direction. These personal finance tips for 2026 give you a clear, repeatable system to spend with intention, pay down debt faster, and grow savings even when prices feel stubbornly high. You do not need a finance degree, just a plan you will actually follow.
Inflation has cooled from its peak, but the cost of living remains elevated, and real wages still lag for many households. That makes a deliberate approach more valuable than ever. Let us walk through the exact moves that move the needle.
Start With the Personal Finance Tips That Matter Most
Most financial advice fails because it tries to fix everything at once. Instead, focus on the few levers that drive the biggest results. From years of coaching friends through money stress, three habits consistently outperform the rest.
- Automate your savings before you can spend the money.
- Attack high-interest debt with urgency, since it compounds against you.
- Track spending weekly, not monthly, so small leaks surface fast.
Nail these three and you solve most money problems before they grow. Everything else is refinement.
Build a Budget You Will Not Abandon
The 50/30/20 framework remains the easiest starting point: 50% of take-home pay for needs, 30% for wants, and 20% for savings and debt repayment. If those ratios feel impossible in your city, adjust them, but keep the savings slice sacred. A budget you tweak beats a perfect budget you quit.
The Emergency Fund Is Your Financial Seatbelt
Before investing or chasing extra returns, build a cash cushion. Aim for three to six months of essential expenses in a high-yield savings account. In 2026, the best online savings accounts still pay competitive annual percentage yields, so your safety net grows while it sits.
| Goal | Target Amount | Where to Keep It |
|---|---|---|
| Starter buffer | $1,000 | High-yield savings |
| Full emergency fund | 3-6 months of expenses | High-yield savings |
| Short-term goals | Varies | Money market or CDs |
| Retirement | 15% of income | 401(k) / IRA |
This buffer stops a surprise car repair from becoming credit card debt. It is the single most underrated step in any financial plan.
Why Do Most Budgets Fail Within Three Months?
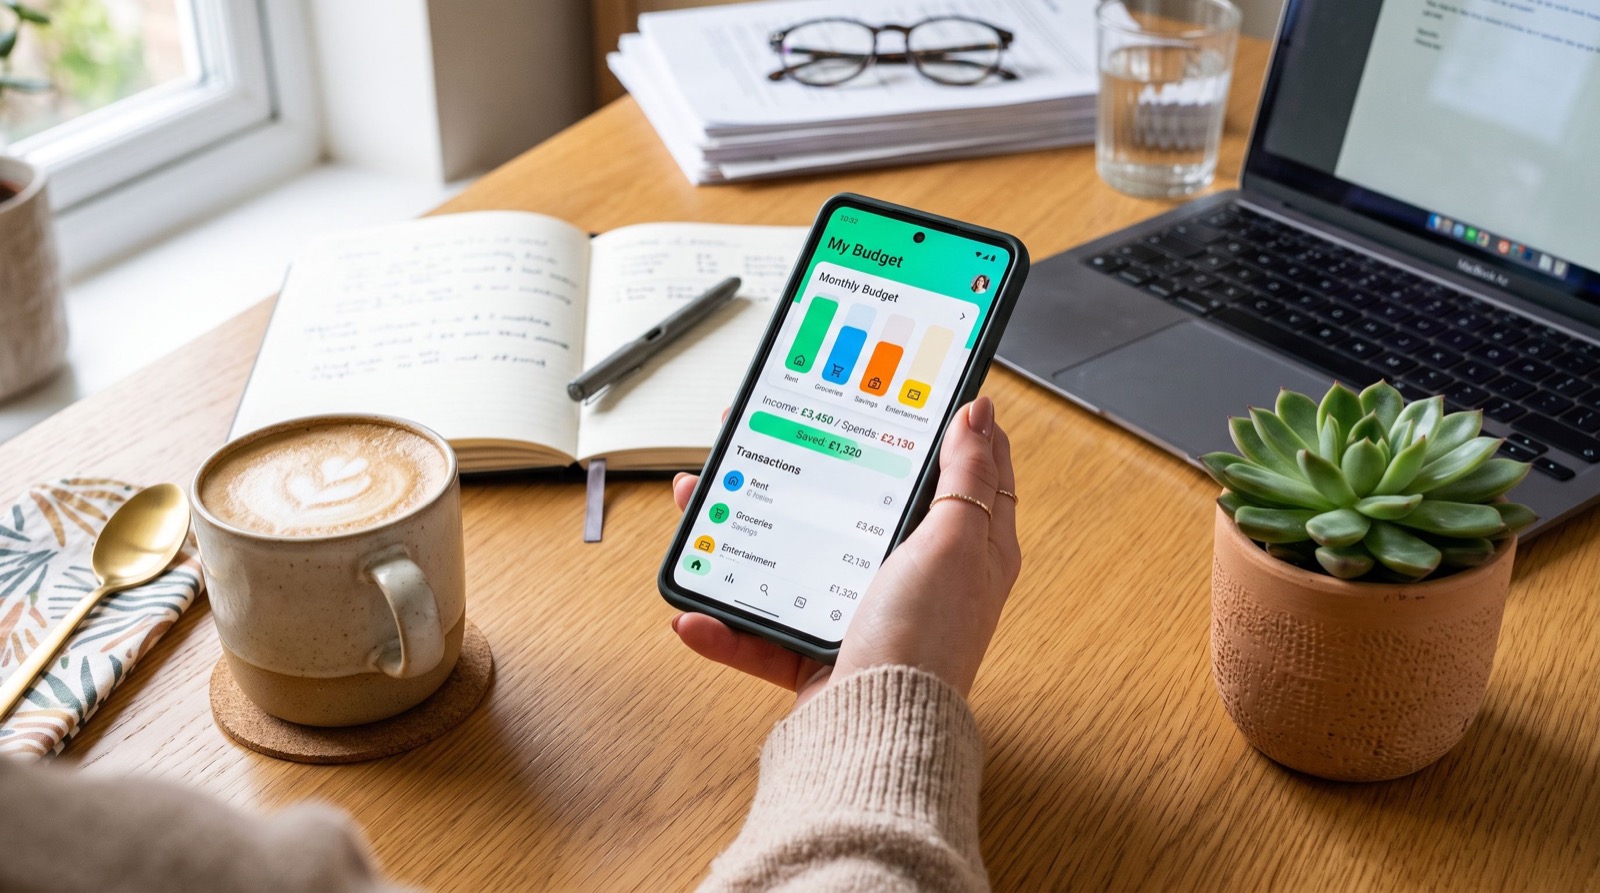
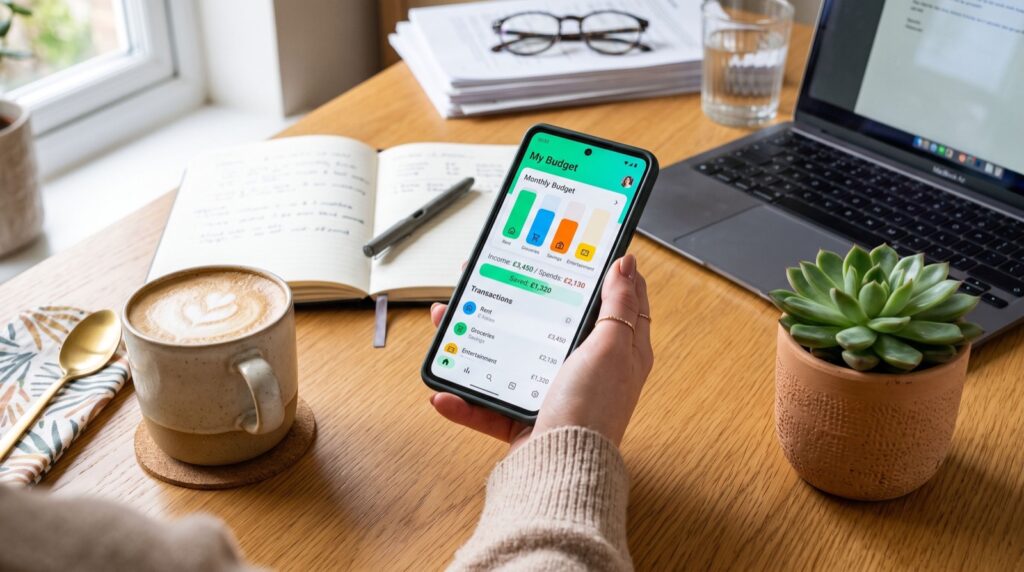
Budgets collapse for one reason: friction. When tracking takes effort, people stop. The fix is to remove the manual work. Link your accounts to a trusted app that categorizes transactions automatically and sends gentle alerts when a category runs hot.
The right tools turn discipline into a default. If you want curated, beginner-friendly personal finance tips that match real tools to real goals, lean on a dedicated money resource instead of piecing advice together from scattered threads. And to compare the platforms that automate the heavy lifting, this roundup of the best money apps breaks down what each one does well.
Features Worth Looking For in a Money App
- Automatic transaction categorization and spending insights.
- Customizable savings goals with progress tracking.
- Bill reminders to avoid late fees.
- Bank-level encryption and two-factor authentication.
- Free or low-cost tiers with no hidden charges.
Crush Debt With a Clear Strategy
High-interest debt is wealth in reverse. Average credit card APRs sit above 21% in 2026, which means a balance can double in just a few years if ignored. Pick one of two proven methods and commit.
- Avalanche: Pay minimums on everything, then throw extra cash at the highest-interest balance. This saves the most money.
- Snowball: Pay off the smallest balance first for a quick psychological win, then roll that payment forward.
Either works. The best method is the one you will stick with. For guidance grounded in research, the CFPB’s debt management resources offer free, unbiased tools worth bookmarking.
Invest Early, Even in Small Amounts
Time in the market beats timing the market. Thanks to compounding, a 25-year-old investing $200 a month can accumulate far more than a 35-year-old investing twice as much, simply because the money has a decade longer to grow. Start with tax-advantaged accounts.
Prioritize any employer 401(k) match first, because it is an instant 100% return. The SEC’s compound interest calculator lets you see exactly how your contributions snowball over time, which is a powerful motivator.
When you choose where to put your long-term money, treat it with the same care you would use selecting reputable service experts for any important job. Vet the fees, read the fine print, and favor low-cost index funds over flashy picks.
Protect Your Progress and Avoid Lifestyle Creep
Earning more only builds wealth if your spending does not rise to match. Lifestyle creep is the silent wealth killer, and it sneaks in through small, “deserved” upgrades that quietly reset your baseline. A raise becomes a bigger car payment, a bonus becomes a pricier apartment, and your savings rate never moves.
Beat it with a simple rule: every time your income rises, send at least half of the increase straight to savings or investments before you adjust your lifestyle. You still enjoy the raise, but your future self gets paid first.
Review these guardrails during your weekly money check-in:
- Keep fixed costs, especially housing and transportation, within sustainable limits.
- Give every raise a job before it hits your checking account.
- Wait 48 hours before any non-essential purchase over a set threshold.
- Revisit recurring subscriptions quarterly and cancel the dead weight.
Set Goals You Can Actually Picture
Abstract goals like “save more” rarely survive a tough month. Concrete, time-bound targets do. Instead of a vague intention, write “save $6,000 for a home down payment by December 2026.” The specificity gives your brain something real to chase and makes progress measurable.
Break each big goal into monthly milestones, then automate a transfer that hits the milestone without any effort on your part. When the goal, the deadline, and the automation all line up, consistency stops depending on motivation and starts running on autopilot.
Frequently Asked Questions
How much should I save from each paycheck?
A common target is 20% of take-home pay split between savings, debt repayment, and investing. If that is out of reach, start with even 5% and increase the rate by one percentage point every few months until you hit your goal.
Should I pay off debt or invest first?
Capture any employer retirement match first, since it is free money. After that, prioritize paying off high-interest debt above roughly 7% to 8%, because few investments reliably beat that guaranteed return.
What is the fastest way to improve my credit score?
Lower your credit utilization by paying balances down below 30% of your limit, make every payment on time, and avoid opening several new accounts at once. Utilization and payment history carry the most weight.
Are budgeting apps safe to use?
Reputable apps use bank-level encryption and read-only connections, meaning they cannot move your money. Always enable two-factor authentication and review each app’s privacy policy before linking your accounts.
Final Thoughts
Wealth is built through boring consistency, not dramatic wins. Apply these personal finance tips one at a time, automate everything you can, and review your progress weekly in 2026. Within a year you will likely have a funded emergency account, shrinking debt, and growing investments, all from a plan simple enough to stick with for life.